What the forecasts are saying about the property market in 2026
Property market predictions 2026 are diverging sharply. Some forecasters expect Melbourne property prices to decline, whilst others predict growth. This matters because your buying strategy changes completely depending on which scenario unfolds. At Your Australian Property Buyers Agents, we’ve spent 30+ years watching how buyers respond to market forecasts.
Property buyer analysing market data and documents for property market predictions 2027 on a laptop at a desk
The reality is messier than any single forecast suggests. You’ll see predictions ranging from a 4-8% fall in house prices to growth forecasts of 6.8% in 2026 and 7.3% in 2026. Both can’t be right. Both might be wrong. What matters isn’t picking the winner, it’s understanding what drives each forecast and building a strategy that works regardless.
The bearish case: Domain’s forecast of declining prices
Domain’s FY2027 forecast predicts Melbourne house prices will fall 4-8% over the year to June 2026, according to Everstone Finance’s analysis of Domain forecasts. This is the most widely cited negative prediction.
Why is Domain predicting a downturn? The forecast reflects rising interest rates, slowing buyer demand, and tighter lending conditions. When fewer buyers can borrow, fewer buyers compete for properties. Prices adjust downward. It’s mechanical. The question isn’t whether this could happen, it’s whether the conditions that trigger it actually materialise.
Here’s where experience matters: forecasters extrapolate recent trends and assume they continue. They don’t always account for the buyers who sit out one cycle and return when conditions shift. A 5% price fall sounds catastrophic until you realise that buyer who waited is now competing again, and the fall stops.
The bullish case: growth forecasts from other analysts
A separate forecast reported on LinkedIn projects Melbourne house prices will rise 6.8% in 2026 and a further 7.3% in 2026. This directly contradicts Domain’s prediction. The LinkedIn post doesn’t specify the underlying forecaster or methodology, which limits how much weight we can give it.
KPMG’s August 2026 forecast splits the difference. According to KPMG’s housing market analysis, KPMG forecasts a 5.0% decline in Melbourne house prices during 2026, followed by a 3.3% rebound in 2026. This is the middle ground: prices fall, then recover.
Why do some forecasters expect growth? They point to population growth, limited housing supply, and eventual interest rate cuts. When rates fall, borrowing becomes easier. Demand returns. Prices rise. The timing is everything, and nobody can predict when the Reserve Bank will move.
Melbourne house price forecast 2026: what’s expected for houses versus units
The forecasts consistently show one pattern: houses face tougher conditions than units. This distinction is critical for your strategy.
Houses: the softer outlook
Melbourne houses are forecast to experience larger price falls than units across most predictions. Domain forecasts a 4-8% decline for houses versus 1-3% for units. KPMG forecasts a 5.0% fall for houses in 2026 with a 3.3% rebound in 2026.
Why? Detached houses appeal primarily to owner-occupiers with families. These buyers are most affected by interest rates because they’re stretching their budgets further. When rates rise, fewer families can qualify for loans. Demand drops. Investors, by contrast, buy units for rental yield, a different calculation entirely. They’re less rate-sensitive.
This doesn’t mean you shouldn’t buy a house in 2026. It means you need to be strategic. If you’re buying a house, focus on location fundamentals: proximity to schools, transport, established suburbs with long-term demand. Don’t buy based on the assumption prices will rise.
Units: a more resilient picture
Units are forecast to hold value better than houses. Domain’s 1-3% decline is gentler than the 4-8% fall predicted for houses. KPMG expects units to rise 0.4% in 2026. The difference reflects investor demand: units attract investors seeking rental yield. Investors aren’t as rate-sensitive as owner-occupiers because they’re not stretching personal budgets.
But resilience isn’t the same as growth. A unit market that’s flat or slightly down is still a market where you need to negotiate hard and avoid overpaying. A 1% fall over 12 months is still a fall.
What most buyers don’t see is that unit performance varies dramatically by location and type. A newer apartment in an oversupplied area behaves very differently from an established unit in a tight suburb. Forecasts treat the market as monolithic.
Melbourne property prices 2026: how to interpret competing predictions
You’re looking at forecasts that range from -8% to +7%. That’s a 15-percentage-point spread. How do you make a decision when experts disagree this widely?
Why forecasts are unreliable and what to focus on instead
Forecasts are educated guesses. They’re useful for understanding the scenarios forecasters think are plausible. They’re dangerous when you treat them as predictions. The difference is subtle but critical.
A forecast says “if these conditions hold, this outcome is likely.” A prediction says “this will happen.” Forecasts come with assumptions. When the assumptions change, the forecast breaks. Interest rates might not fall when KPMG expects. Population growth might slow.
Buyers who chase forecasts often lose. They either overpay waiting for growth that doesn’t come, or they underbid waiting for falls that don’t happen. The buyers who win focus on fundamentals: Is this property worth the price I’m paying?
These questions don’t depend on whether prices rise 7% or fall 5%. They depend on the property itself, the location, and your financial position.
The real drivers: interest rates, supply and buyer demand
Forget the forecasts for a moment. What actually moves property prices?
Interest rates are the primary lever. When the Reserve Bank raises rates, borrowing costs increase. Buyers can borrow less. Demand falls. Prices adjust. When rates fall, the reverse happens.
Supply matters enormously. Melbourne has tight supply in established suburbs and oversupply in new apartment precincts. A suburb with limited new stock behaves completely differently from one flooded with new units.
Buyer demand is the third pillar. Population growth, interstate migration, overseas investment, and investor activity all influence demand. Melbourne has been a migration magnet. That’s changed the market fundamentally.
The property market predictions 2026 that matter most aren’t the headline numbers. They’re the assumptions underneath. Find a forecast, read the fine print, and ask: do these assumptions still hold?
Melbourne property investment strategy for an uncertain 2026
You can’t control whether prices rise or fall in 2026. You can control your strategy. Here’s how to think about it.
Build your investment strategy on properties that work in any market. A rental property that delivers 4% gross yield works whether prices rise 5% or fall 5%. The yield is real. The price movement is noise.
When you’re evaluating an investment property, calculate the rental return first. What’s the annual rent? Divide by the purchase price. That’s your gross yield. Now ask: is that yield acceptable to me? If prices rise, it’s a bonus. If prices fall, you still have the rental income. This is how you avoid the trap of buying based on price forecasts.
The same logic applies to location. Invest in suburbs with strong rental demand, good transport, and established amenities. These locations attract tenants consistently, regardless of whether the broader market is rising or falling.
How to build a strategy that works in any market
Your strategy should have three components: cashflow, capital growth, and risk management.
Cashflow means the rental income covers your costs, mortgage, rates, insurance, maintenance. If it doesn’t, you’re speculating on price growth. That’s not investment, that’s gambling. In an uncertain market, cashflow is your safety net.
Capital growth is a bonus, not the plan. If you buy a property with positive cashflow and prices rise, you win twice. If prices fall, you still have the income. This removes the pressure to time the market perfectly.
Risk management means diversification and due diligence. This is where professional buyer representation makes a difference, we help you identify risks most buyers miss, and our Property Due Diligence service ensures you have the data and analysis to make confident decisions.
What buyers should do now to prepare for 2026
The forecasts create uncertainty. Uncertainty creates opportunity for buyers who prepare. Here’s what you need to do now.
Get your finances sorted before the market moves
Interest rates might fall in 2026. They might rise. Either way, your borrowing capacity is determined now. Get pre-approved for finance. Understand exactly how much you can borrow and at what rate. Don’t rely on estimates, get a formal pre-approval from your lender.
This matters because when opportunities emerge, you need to move fast. If a property hits the market that ticks all your boxes, you can’t afford to spend two weeks getting finance sorted. By then, it’s gone. Pre-approval means you’re ready.
Also, lock in your rate if you can. If you’re paying down debt before buying, focus on high-interest debt first. A credit card at 18% is a worse investment than almost any property. Clear that first. Then build your deposit.
Build your knowledge of comparable sales and true value
This is where most buyers fail. They look at a property, like it, and make an offer based on the asking price or their emotion. They don’t know what comparable properties actually sold for.
Comparable sales data is your anchor to reality. When you understand what similar properties sold for recently, you know whether a property is overpriced, fairly priced, or a genuine opportunity.
Start building a database of recent sales in the suburbs you’re targeting. Track what sold, what price, when, and how long it took. Look for patterns. Which properties sold quickly? Which lingered? Why?
Access off-market opportunities before they hit the open market
Here’s what most buyers don’t see: the best properties never hit the major portals.
Off-market properties have less competition. Fewer buyers know about them. You’re negotiating against fewer rivals. That’s your advantage.
Access to off-market properties Melbourne is one of the key differences between buying alone and working with experienced buyer advocates. We have relationships across the market.
The property market predictions for 2026 show divergence because the future is genuinely uncertain. Interest rates, supply, and buyer demand could move in multiple directions.
Focus on properties with strong fundamentals: good location, fair price, and positive cashflow if you’re investing.
Your Australian Property Buyers Agents helps buyers do exactly this.
Ready to build a property strategy that works in any market? Book a free strategy call with our team.
Frequently Asked Questions
Will Melbourne property prices rise or fall in 2026?
The forecasts conflict. Domain’s FY2027 report predicts house prices down 4–8% and units down 1–3%. KPMG forecasts a 5% house-price decline in 2026, then a 3.3% rebound in 2026. A separate analyst forecast predicts growth of 6.8% in 2026 and 7.3% in 2026. No single consensus exists. Rather than betting on a forecast, focus on buying the right property at the right price for your goals, regardless of short-term market direction.
Which property types are expected to perform better in 2026?
Forecasts suggest units may be more resilient than houses in 2026. Domain’s FY2027 outlook shows a smaller predicted decline for units (1–3%) compared to houses (4–8%). However, performance depends heavily on location, rental demand, and investment fundamentals. A well-positioned property in strong demand always outperforms a poorly chosen one, regardless of property type.
How should I use these forecasts to make a buying decision?
Treat forecasts as context, not certainty. They help you understand market sentiment but shouldn’t drive your decision. Instead, focus on comparable sales, rental yield (for investors), location strength, and whether the property meets your needs at a fair price. Property selection is only one part of success; due diligence and negotiation matter far more. Professional assessment of the specific property’s value and risk is your best protection.
Is 2026 a good time to buy property if prices might fall?
If you’re buying for the right reasons—to live in it, build long-term wealth, or secure investment-grade assets—timing the market is less important than buying well. Falling prices can mean better opportunities for disciplined buyers who do their due diligence and negotiate hard. Rising prices reward those who move decisively with the right strategy. Either way, the goal is the right property at the right price, not predicting the market.
Key Takeaway Investment property buyers who succeed focus on avoiding mistakes as much as finding the right asset. Due diligence, comparable sales analysis, and strategic negotiation determine the outcome far more than property selection alone.
Property Investment Risks Melbourne: What Can Go Wrong
Investment property buyers face real financial risk at every stage.
The biggest risk isn’t a property that looks bad. It’s one that looks good but performs poorly.
Here’s where buyers get it wrong: they focus on the property and ignore the context.
Common investment property risks in Melbourne include:
Rental demand risk: The property looks desirable, but tenants don’t want to live there. Vacancy rates spike. You’re carrying the mortgage on an empty property.
Structural and maintenance risk: Hidden defects emerge after purchase. Repairs cost tens of thousands. Your cash flow disappears.
Market risk: You buy at the peak of a cycle. Growth stalls. You’re locked into a property that’s losing value or stuck in neutral.
What most buyers don’t see is that these risks compound. A property with weak rental demand and rising maintenance costs becomes a liability fast.
Watch Out Many investment property buyers skip proper due diligence to move quickly. This creates exposure to structural defects, overvaluation, and poor rental performance. The cost of getting it wrong can be significant in lost equity, cash flow, or repairs.
Property Due Diligence Melbourne: The Steps That Separate Winners
Property due diligence is where investment property buyers either protect themselves or expose themselves to catastrophic risk. It determines whether a property is actually worth buying.
Professional property buyer and agent reviewing inspection reports, architectural plans and property details at a dining table with laptop, notepad and documents visible in natural lighting
Financial due diligence: numbers before emotion
Before you fall in love with a property, the numbers need to work. Financial due diligence means stress-testing the investment against realistic scenarios: does it cash flow, what happens if vacancy spikes or rates rise, and what’s your exit strategy?
Investment property buyers need to calculate:
Gross rental yield: Annual rental income divided by purchase price. If a property yields significantly less, the numbers need to justify it through capital growth expectations.
Net cash flow: Rental income minus all costs (mortgage, rates, insurance, maintenance, vacancy allowance, body corporate fees). Many properties look good on gross yield but bleed cash every month.
Serviceability: Can you service the loan if rates rise 2-3%? If interest rates spike, do you have enough buffer to keep the property, or are you forced to sell at the wrong time?
Here’s where experience matters: most investors calculate yield and stop. They don’t model worst-case scenarios or account for vacancy, maintenance spikes and rate rises.
Pro Tip Before making an offer, model your investment under three scenarios: base case (current rates, average vacancy), stress case (rates +2%, 8 weeks vacancy annually), and worst case (rates +3%, 12 weeks vacancy). If the property doesn’t cash flow in stress case, walk away.
Physical inspection and structural assessment
A professional building inspection is non-negotiable for investment property buyers. You’re looking for defects that cost money to fix, major structural issues, roof problems, plumbing failures, electrical hazards and asbestos exposure can be costly to remediate.
Inspection reports often reveal problems the seller hasn’t disclosed, which shifts the negotiation entirely. You can renegotiate price, request repairs, or walk away with your deposit intact.
Rental demand and tenant appeal
Investment property buyers need to think like a tenant, not an owner. Will tenants want to rent this property? How quickly can you fill a vacancy?
Here’s what most buyers overlook: a property might be affordable to buy but unattractive to rent.
Assess rental demand by looking at:
Comparable rental properties: What are similar properties renting for? How long do they typically stay vacant? Is demand increasing or declining?
Tenant demographics: Who wants to live in this area? Young professionals, families, students, retirees? Does the property suit the target tenant?
Amenities and transport: Is the property close to public transport, shops, schools, or employment hubs? These drive tenant demand.
Investment property buyers who focus on rental demand upfront avoid the painful experience of owning a property nobody wants to rent.
Comparable Property Sales Melbourne: How to Avoid Overpaying
Overpaying is the fastest way to destroy investment returns. Many investment property buyers rely on automated valuations or agent estimates, both are often wrong.
Here’s where buyers get it wrong: they compare properties superficially. A three-bedroom house in Footscray isn’t comparable to a three-bedroom house in Hawthorn. Location, condition, size, and timing all matter.
Proper comparable sales analysis requires:
Recent data: Sales from the last 3-6 months are most relevant. Older sales don’t reflect current market conditions.
True comparables: Properties must be genuinely similar in location, size, condition, and type. A renovated property isn’t comparable to one needing work.
Adjustment for differences: If a comparable sold for more, why? Better condition? Larger land? Better location? You need to understand the price drivers.
Investment property buyers who understand comparable sales negotiate with confidence.
Pro Tip Request sales data from the last 90 days for at least five comparable properties. Calculate the average price per square metre. Compare your target property against this benchmark. If it’s priced above comparable sales without a clear reason, you’re likely overpaying.
Melbourne Property Investment Strategy: Building Your Portfolio
Successful investment property buyers don’t buy randomly. They buy strategically, defining what they’re trying to achieve, then building a portfolio that delivers it.
Defining your investment criteria
Before you start looking at properties, define your investment criteria. Too many investment property buyers browse listings without clarity, fall in love with properties that don’t fit their strategy, chase deals that don’t align with their goals, and waste time and money.
Investment objective: Are you chasing cash flow, capital growth, or a mix? Cash flow properties typically yield 4-6% but appreciate slowly. Growth properties might yield 2-3% but appreciate faster. Your strategy determines which properties you should buy.
Budget and financing: How much capital do you have? How much can you borrow? What deposit percentage are you comfortable with? This defines your price range and the properties you can actually pursue.
Location parameters: Which suburbs or areas align with your strategy? A cash flow strategy might favour established areas with strong rental demand. A growth strategy might favour emerging areas with infrastructure development.
Investment property buyers with clear criteria make faster decisions, avoid distractions, and build portfolios that actually deliver their goals.
Timing, negotiation and when to walk away
Timing matters. Negotiation matters more. But knowing when to walk away matters most.
The best investment property buyers understand that not every property deserves an offer. Sometimes the best decision is to keep looking.
Here’s where experience matters: you need to know when a deal is genuinely good and when it just looks good.
Negotiation strategy depends on market conditions and your leverage.
Investment property buyers who negotiate well understand:
Your walk-away price: Know the maximum you’ll pay before you start negotiating. Stick to it. Emotion will tempt you to go higher. Don’t.
The seller’s position: Are they desperate to sell? Do they have multiple offers? Are they flexible on timing? This shapes your negotiation strategy.
Your leverage: If the property has been on market for months, you have leverage. If it’s generating multiple offers, you don’t. Adjust accordingly.
Common Mistakes Investment Property Buyers Make
Investment property buyers typically make the same mistakes repeatedly.
Mistake 4: Not stress-testing the numbers. They calculate yield under perfect conditions and don’t model vacancy rises, rate spikes or maintenance blowouts.
Mistake 7: Not negotiating properly. They accept the asking price or negotiate weakly, leaving tens of thousands of dollars on the table.
These mistakes are avoidable. They require discipline, data and strategy, and most investment property buyers lack all three.
How Professional Buyer Representation Changes the Outcome
Investment property buyers who work with experienced buyer advocates typically secure better properties at better prices. We’re incentivised to find you the right property at the right price. Professional buyer representation changes the process at every stage.
Property search: Instead of browsing public listings like everyone else, we access off-market and pre-market opportunities through relationships with agents, developers and other buyers.
Valuation and negotiation: We analyse comparable sales data, establish true market value and negotiate on your behalf, knowing when to push hard and when to walk away.
Speed and efficiency: Most clients secure a property within 60 days.
The cost of professional buyer representation is far less than the cost of overpaying or buying the wrong property.
Best For Property investors building or expanding a portfolio who want independent research, due diligence, and negotiation support. Also suited to interstate or overseas buyers who need trusted local expertise and access to off-market opportunities.
Conclusion: The Right Property at the Right Price
Investment property buyers succeed when they treat property purchase as a strategic process, not an emotional decision. It’s to buy the right Melbourne property, at the right price, without costly mistakes.
Victorian Civil and Administrative Tribunal guidance on residential tenancy disputes
Australian Taxation Office resources on investment property deductions and capital gains tax
Consumer Affairs Victoria information on property buying and selling obligations
Ready to secure the right investment property without costly mistakes? Book a free strategy call with Your Australian Property Buyers Agents.
Investment Property Buyers: Key Stages
Focus Area
Why It Matters
Property Search
Access to off-market opportunities
First-mover advantage and better negotiating position
Due Diligence
Financial modelling, inspections, rental demand
Avoid overpaying and structural risk
Comparable Sales
Market value analysis
Negotiate with confidence and data
Negotiation
Strategic positioning and leverage
Potential savings of $10,000’s or even $100,000’s
Portfolio Strategy
Alignment with investment objectives
Ensure properties deliver your goals
Frequently Asked Questions
What should investment property buyers look for when assessing a property?
Investment property buyers should focus on four core areas: financial fundamentals (rental yield, capital growth potential, cash flow), location strength (tenant demand, transport, amenities, school proximity), physical condition (building integrity, maintenance costs, age of major systems), and market position (comparable sales, vacancy rates, competitor properties). Most buyers fixate on the property itself. Winners assess whether the numbers stack up, whether tenants will actually want to live there, and whether the price reflects true value. The property may look right. The numbers still need to justify the investment.
How can investment property buyers avoid overpaying?
Avoid overpaying by grounding your offer in comparable property sales data, not agent valuations or emotional attachment. Analyse recent sales of similar properties in the same suburb, not asking prices, actual sold prices. Understand what you’re paying for: location premium, condition, rental appeal, or scarcity. Set your maximum offer before you inspect the property and stick to it. Most buyers negotiate upwards as they fall in love with a property. Strategic buyers know when to walk away. If the asking price is significantly above comparable sales, question why. Often there’s no good reason.
What are the main risks when buying an investment property?
Investment property risks fall into three categories: financial (negative cash flow, rising interest rates, unexpected maintenance), market (oversupply reducing rental demand, capital depreciation, changing suburb dynamics), and operational (problem tenants, vacancy periods, management costs). Many buyers underestimate holding costs, rates, insurance, maintenance and vacancy periods can exceed rental income, especially in the first years. Location risk matters more than property condition. A well-maintained property in a declining suburb will underperform a modest property in strong demand. Assess not just the property, but the suburb’s long-term demand drivers: employment, infrastructure, population growth, school quality.
Should investment property buyers leverage a buyer’s agent?
A buyer’s agent is valuable if you lack local market knowledge, don’t have time to conduct thorough due diligence, want access to off-market opportunities, or need skilled negotiation to secure better terms. Experienced agents understand comparable sales data, can assess rental appeal, identify hidden risks, and negotiate strategically. They work exclusively for you, not the vendor or developer. For interstate or overseas investors, local representation is almost essential. For local investors with time and expertise, a buyer’s agent is optional. The real question isn’t whether you can afford one, it’s whether you can afford to overpay or buy the wrong property without one.
Buyers agents in Australia are licensed professionals who act exclusively for the purchaser, sourcing property, running due diligence, assessing value against comparable sales and negotiating terms. Choosing one comes down to three checks: verify the licence, confirm they represent buyers only, and test whether they can explain value with evidence rather than opinion.
Ask for their Victorian licence number and check it against the Consumer Affairs Victoria licensing register.
Never waive a building and pest inspection to make your offer more attractive.
Under Victorian rules, an auction contract is unconditional once the hammer falls, with no cooling-off.
Set your walk-away number in writing before auction day, based on comparable sales, not the reserve.
A buyer’s agent earns their keep when competition is fierce or you are buying from interstate or overseas.
What Buyers Agents in Australia Actually Do Behind the Scenes
Most people think a buyer’s agent finds a property and bids on it. That’s the visible 10%. The other 90% is where money is made or lost, and it happens long before an auctioneer raises a hand. Buyers agents in Australia are licensed professionals who act exclusively for the purchaser, sourcing property, running due diligence, assessing value against comparable sales and negotiating terms. This guide from Your Australian Property Buyers Agents covers what that work actually involves and how to pick someone worth hiring.
The property may look right. The numbers still need to stack up. That gap between appearance and evidence is the entire job.
How to Choose a Buyers Agent Without Getting Burned
Choosing well comes down to three checks: verify the licence, confirm they represent buyers only, and test whether they can explain value with evidence rather than opinion. A polished website proves nothing. Ask for their Victorian licence number and check it against the Consumer Affairs Victoria licensing register.
Licensing, Independence and the Questions That Expose a Weak Operator
Independence is the fault line. An agent who also sells property, or takes referral fees from developers, has a conflict you cannot see. These questions separate the operators from the order-takers:
Which licence do you hold, and what is the number?
Do you ever act for sellers or developers?
How do you get paid, and does any third party pay you?
Can you walk me through three recent comparable sales and why you chose them?
What would make you tell me not to buy?
That last question matters most. The best advice is sometimes to walk away, and an agent who cannot say those words is a salesperson in disguise.
Buyers Agent Due Diligence: Where Deals Are Made or Broken
Due diligence is the process of verifying a property’s value, condition, title and risks before committing. It covers building and pest inspection, contract review by a solicitor, planning overlays, title searches and comparable sales analysis. Skipping it because a property “feels right” is how buyers inherit structural defects, illegal renovations or a price built on hope.
We see this all the time: a buyer falls for the kitchen, then discovers the extension was never permitted. Facts before photos. Every time.
Watch Out Never waive a building and pest inspection to make your offer more attractive. In a competitive market that tactic wins auctions and loses money, because defects found afterwards are yours to fund.
Buyers Agent Property Negotiation: The Skill You Are Really Paying For
Negotiation is the core service, and it is not about being tough. It is about knowing what the property is worth, what the vendor needs, and where their flexibility ends. A buyer’s agent negotiates with evidence: comparable sales, days on market, conditions and the vendor’s motivation. That evidence, not bravado, moves a price.
A buyer’s agent and a couple reviewing comparable sales printouts and a laptop on a kitchen table in a Melbourne home, mid-conversation, afternoon light
Here’s where buyers get it wrong. They negotiate on emotion and reveal their ceiling in the first conversation. Experience teaches the opposite: ask questions, stay quiet, let the selling agent talk. The deal can change on a single condition, not just the number.
Buyers Agent Auction Bidding: Why the Bidding Is the Easy Part
Bidding at auction is the simplest part of the process. The hard work is the valuation, the contract review and the bidding strategy set beforehand. Auction day rewards preparation: a firm walk-away price, a bidding sequence that doesn’t reveal your hand, and the discipline to stop.
Under Victorian rules, an auction contract is unconditional once the hammer falls. No cooling-off, no finance clause. That single fact should shape your entire approach.
Pro Tip Set your walk-away number in writing before auction day, based on comparable sales, not the reserve or the crowd. The atmosphere is designed to move you. A written number doesn’t.
How Buyers Agents Charge and What You Get for It
Fees vary by engagement, so ask for a written quote and confirm exactly what it covers.
Fee Structure
How It Works
Best For
Watch For
Fixed fee
Set amount agreed upfront
Buyers who want certainty
Scope limits
Percentage of purchase price
Fee scales with price
Higher-value purchases
Incentive to pay more
Engagement plus success fee
Upfront retainer, balance on settlement
Long search campaigns
Total cost clarity
Success-only
Paid when you buy
Unsure buyers
Higher rate overall
Ask what happens if nothing is bought.
When a Buyers Agent Is Worth It and When It Is Not
A buyer’s agent earns their keep when competition is fierce, when you cannot inspect during business hours, or when you are buying from interstate or overseas and need local eyes. They add less value in a quiet market where stock is plentiful and you have time to research thoroughly.
For investors, the case often rests on selection quality and avoiding overpaying. For first-home buyers, it rests on guidance through a process designed to confuse. Our property negotiation service exists because that gap is real.
Key Takeaway The right question isn’t “can I afford an agent?” It’s “what does one mistake cost me?” On a significant purchase, a single misjudged bid can dwarf any fee.
The Bottom Line on Buyers Agents in Australia
Buying well is about what you avoid as much as what you buy. Buyers agents in Australia are worth the fee when they bring evidence, independence and negotiation discipline to a decision most people make only a few times in their lives.
That’s the standard we hold ourselves to at Your Australian Property Buyers Agents. With 30+ years of property experience, independent buyer-only representation and access to off-market opportunities, we assess value, risk and resale potential before you commit. Most clients secure the right property within 60 days.
Frequently Asked Questions
What does a buyers agent do?
A buyers agent acts only for the buyer. That means searching on and off market, appraising value against comparable sales, running due diligence, negotiating price and terms, and bidding at auction on your behalf. The visible part is the property shortlist. The real work sits behind it: checking title and planning overlays, pressure-testing the vendor’s price expectations, and knowing when a property is not worth an offer. A good agent will also tell you to walk away when the numbers do not stack up.
Are buyers agents worth it when buying property?
It depends on what you are buying and how well you know the market. In a competitive Melbourne auction or a tightly held suburb, independent representation can stop you overpaying or missing a property because of a weak bidding strategy. The value is strongest when you are time-poor, buying interstate or overseas, or competing for off-market stock. If you are experienced, know the suburb intimately and have months to spare, the case is weaker. Ask any agent to explain exactly what they control in the process before you commit.
How do I choose a reliable buyers agent?
Check the licence first. In Victoria, estate agents and buyers agents must hold a licence or work under one, and you can verify it through the Business Licensing Authority. Then test independence: ask whether the firm or anyone connected to it sells property or takes developer incentives. Ask for recent comparable sales they have analysed in your target suburbs, how they handle due diligence, and what happens to their fee if nothing suitable is found. Vague answers on any of these are a warning sign.
Can a buyers agent negotiate a better property price?
A skilled negotiator can often improve the outcome, but no one can promise a set discount. The advantage comes from information and discipline: knowing what comparable properties actually sold for, understanding the vendor’s motivation, and not being emotionally attached to the property. Buyers who negotiate alone tend to reveal their budget and fall in love with the home. An agent who negotiates for a living can hold the line on price and conditions. Ask for their process, not a guaranteed saving.
The market will not wait for you to feel ready, and the costliest mistakes happen quietly, in due diligence you skipped and a price you didn’t question. If you want independent advice, evidence-based negotiation and someone in your corner who represents only you, book a free strategy call with Your Australian Property Buyers Agents. We’ll show you exactly how the process protects your position, from first inspection to final signature.
What ‘Undervalued’ Actually Means in Melbourne Property
Undervalued investment properties are properties priced below what their location, land size, condition and comparable sales evidence say they should sell for. That gap is where the money is made. Finding it is the hard part.
At Your Australian Property Buyers Agents, we’ve spent 30+ years watching buyers pay too much for the wrong reasons. Here’s the core problem: most buyers search for a property, not a price.
Price vs Value: The Distinction That Costs Buyers Money
Price is what the vendor asks. Value is what the property is actually worth based on evidence.
Those two numbers are often far apart. A tired 1970s brick home in a sought-after pocket can sit on the market for weeks while buyers chase the renovated house next door for more. The renovation looks better. The land value tells a different story.
What most buyers don’t see is the land-to-asset ratio. In suburbs with strong underlying demand, the land does the heavy lifting over time. A dated dwelling on a full block often outperforms a glossy townhouse on a small title.
So how do you find undervalued investment properties? You start with evidence, not emotion.
Key Takeaway Undervalued does not mean cheap. It means the asking price sits below the property’s evidence-based value.
How to Research Comparable Property Sales Melbourne Buyers Rely On
Comparable property sales are the backbone of any valuation. They are recent sales of similar properties in the same or nearby streets, adjusted for size, condition, land and features.
A property professional reviewing sales data and documents on a laptop at a desk in a Melbourne office, with printed floor plans and a notebook nearby
Online estimates are a starting point, not an answer. They lag the market and miss renovations, orientation and street position.
Reading Sales Evidence the Way an Agent Does
Here is how we assess market value:
Pull sales from the last three to six months, not two years
Match land size, frontage and zoning before anything else
Adjust for condition, not emotion
Check days on market and whether a sale was a forced or arm’s-length deal
Compare within the same school zone and street type
A common mistake is comparing a quiet court to a main road. The evidence says they are different markets. Buyers who ignore this overpay.
Victorian land and property sales data gives you a verified starting point for transaction records.
Where to Find Off Market Properties Melbourne Investors Miss
Off market properties are homes sold without public advertising. They never hit the major portals.
This is where the real edge sits. Vendors with a reason to move quietly, and buyers who are ready, meet before the crowd shows up.
This is where experience matters. You need to know the vendor’s motivation, the days on market, and how the evidence compares.
Our approach:
Anchor to comparable sales, never to the asking price
Find out why the vendor is selling and how flexible they are
Present evidence, not opinions
Know your walk-away number before you start
Stay calm when the pressure rises
Australian Securities and Investments Commission on property investment reminds investors to keep emotions out of the decision.
Why Experienced Buyer Representation Changes the Outcome
Most buyers only see five steps. We control the other thirty.
The difference happens behind the scenes: the research, the comparable sales analysis, the relationship with the agent, the negotiation strategy, the due diligence, and the discipline to walk away.
That is the work that determines whether a purchase becomes a strong investment or an expensive lesson.
Our property due diligence and sales data analysis process assesses every property for location, value, risk, rental appeal and future resale potential. We work only for buyers, independent of selling agents.
Watch Out Skipping due diligence to win a competitive negotiation is the fastest way to overpay. The cost shows up years later at resale.
Getting this wrong is expensive. Overpaying on a Melbourne investment property can wipe out years of growth before you even start, and the mistakes are often invisible until it’s too late to fix them.
At Your Australian Property Buyers Agents, we bring 30+ years of experience, independent buyer-only representation, and access to off-market opportunities most buyers never see. We handle the research, due diligence and negotiation that decide the outcome.
Book a free strategy call with our team and secure the right Melbourne property, at the right price.
Frequently Asked Questions
How do you tell if an investment property is undervalued?
An undervalued property sells below what comparable sales evidence supports for its location, land size and condition. Check recent sales of similar properties within the same suburb, adjust for differences in land, layout and renovation, then compare that figure to the asking price or price guide. A property is only undervalued if the gap survives that analysis. A low asking price on its own proves nothing, because it often signals a defect, a difficult title or a vendor testing the market.
Is a low asking price a sign that a property is undervalued?
Usually not. A price guide below comparable property sales Melbourne levels often signals an issue: structural problems, an awkward floor plan, noise exposure, a short lease, or an owner who needs a fast sale. Sometimes it is a deliberate tactic to attract multiple offers and push the price above the guide. Treat any low guide as a prompt to investigate harder, not as a bargain. The numbers only stack up once you have verified the property against real sales evidence.
How do you find off market investment properties?
Off market listings move through relationships, not portals. Build direct contact with selling agents across your target suburbs, tell them your brief clearly, and stay in front of them so they call you before a campaign launches. Vendor database letters, probate and deceased estate sales, and long-held properties also surface stock early. Most buyers never see these opportunities because they only search online. An experienced buyer’s advocate with established agent networks typically hears about them first.
When should you walk away from an investment property?
Walk away when the due diligence uncovers problems the price does not compensate for: building or pest defects, illegal works, flood or bushfire overlays, or a title restriction that limits future development. Walk away when the vendor will not move to a figure the comparable sales support. And walk away when the numbers only work on optimistic assumptions about rent or growth. Not every property deserves an offer, and the best advice is sometimes to keep looking.
Why Granny Flats Are Melbourne’s Smartest Value Play in 2026
Granny flats are self-contained second dwellings built on the same title as an existing house, and they have become one of the most talked-about additions to Melbourne property in 2026. The Housing Industry Association reports that a recent survey of residential building firms found they expected to build 10 times more granny flats in 2026 than in 2022 (HIA, “Granny flats set to take off”). That is not a small shift. It tells you builders are already repositioning for demand.
At Your Australian Property Buyers Agents, we have watched buyers chase this idea for two very different reasons. Some want rental income. Others want family close but not under the same roof.
Both can work. Neither works if the numbers and the permits don’t stack up.
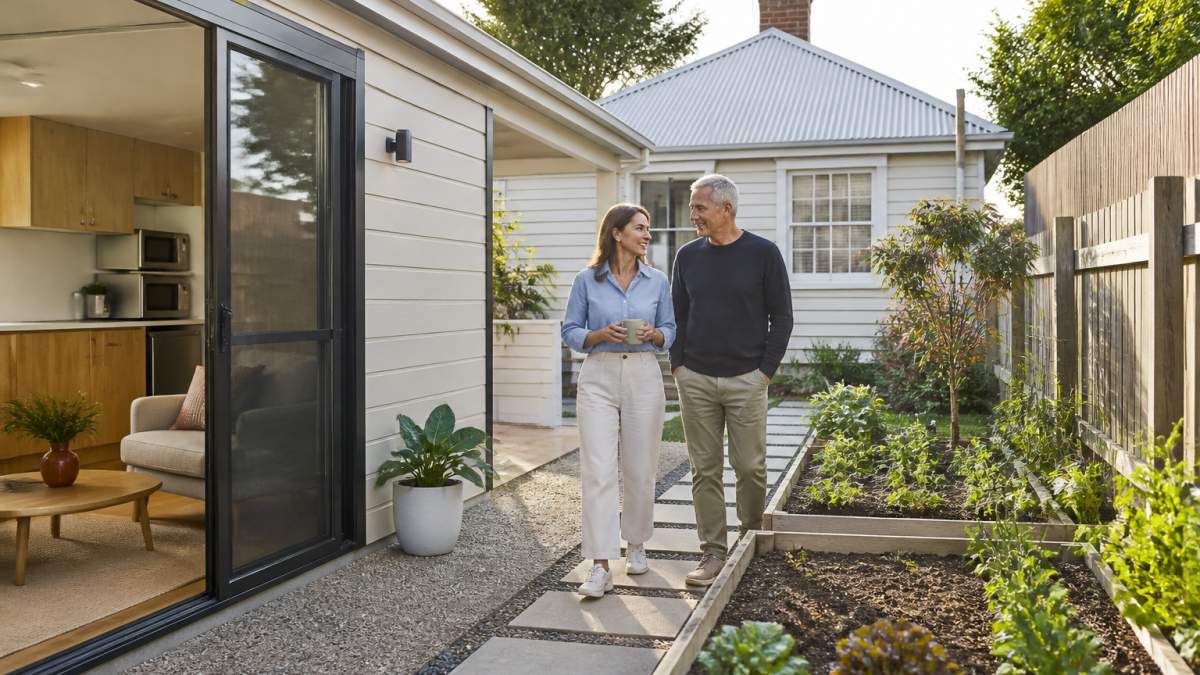
A modern self-contained granny flat in a Melbourne backyard with a paved path, raised garden beds and the main weatherboard house visible in the background under clear afternoon light
The trap is simple. Buyers fall in love with the idea of a granny flat before they check whether the block, the zoning or the title will allow one. We see it constantly. The property looks right. The numbers still need to stack up.
Below, we break down the planning rules, the permit process and the site restrictions that decide whether your granny flat plan is realistic or dead on arrival.
Granny Flat Planning Approval Victoria: What Actually Needs a Permit
Planning approval for a granny flat in Victoria depends on size, siting and the specific rules that apply to your land, not on a single blanket exemption. This is where the most common myth lives.
Many buyers believe any granny flat under 60 square metres needs no approval at all. That is not how the system works.
Watch Out Assuming a sub-60 square metre granny flat is automatically exempt is the single most expensive mistake we see. If the dwelling fails siting, setback or overshadowing rules, you can be ordered to demolish it, and you will have paid for the build twice.
Whether you need a planning permit turns on several factors:
The size and height of the structure
How close it sits to boundaries
Whether it overshadows or overlooks neighbours
Any overlay that applies to your land, such as heritage or a special building overlay
The rules your local council applies on top of the state provisions
The honest answer is that “under 60 square metres” is a useful starting point, not a guarantee. Always confirm the current requirements directly with the Victorian Government’s planning portal and your council before you commit to anything.
The 60 Square Metre Rule Explained
The 60 square metre figure is a threshold that can reduce requirements, not a universal exemption. A smaller dwelling may avoid a planning permit in some circumstances, but only if it also meets siting, setback and coverage rules.
Get one of those wrong and the size becomes irrelevant.
Granny Flat Building Permit Victoria: The Step Most Buyers Underestimate
A building permit is almost always required for a granny flat, even when a planning permit is not. This is the step buyers routinely underestimate.
Building permits cover the structural side: how the dwelling is built, not just where it sits. You will need:
Compliant construction drawings
A registered building surveyor
Documentation that meets the current building regulations
Inspections at set stages of the build
Skip this and you risk an illegal structure that no insurer will cover and no lender will value properly.
Pro Tip Ask your surveyor about the building permit pathway in writing before you exchange on a property you plan to develop. It takes ten minutes and it can save you a six-figure mistake.
Granny Flat Under 60 Square Metres Victoria: What You Can and Cannot Do
A granny flat under 60 square metres in Victoria can often be built with fewer planning hurdles, but it still has hard limits. Size alone does not unlock everything.
Build a compact self-contained dwelling with a bedroom, bathroom and kitchenette
House a family member or use it as a rental, subject to the rules below
Add it to the same title as the main home
What you cannot assume:
That no permit of any kind is needed
That you can ignore setbacks, height limits or site coverage
That the structure can be sold separately from the main house
That last point matters more than most buyers realise. A granny flat on the same title cannot be subdivided and sold on its own unless the land itself can be subdivided.
Granny Flat Rental Rules Victoria: Can You Actually Rent It Out?
You can generally rent out a granny flat in Victoria, but the rules that apply depend on how it is classified and what your council allows. This is where investors need to slow down.
If the dwelling is a lawful second dwelling on the title, renting it is usually straightforward. If it was built without the right permits, renting it exposes you to real risk.
Tenancy laws apply to the granny flat as a separate rental
Your insurer needs to know it is a rental, not a family dwelling
Your lender may treat the property differently once it produces income
Situation
Planning permit
Building permit
Can you rent it?
Small dwelling, compliant siting
Often not required
Required
Usually yes
Larger or poorly sited dwelling
Required
Required
Yes, once approved
Unpermitted structure
Not obtained
Not obtained
No, high risk
We always tell investors the same thing: get the classification right first, then run the numbers. A granny flat that cannot be legally rented is not an income asset, it is a liability.
Site Restrictions That Kill Granny Flat Plans Before They Start
Site restrictions stop more granny flat plans than planning rules ever do. The block, not the paperwork, is usually the real constraint.
What we check before a client commits to a property with granny flat potential:
Block size and shape, including narrow or battle-axe blocks
Available backyard space after setbacks and site coverage
Slope, drainage and easements running through the land
Vehicle access and whether a second driveway is feasible
Overlays that restrict what can be built
Here’s where buyers get it wrong. They buy for the granny flat, then discover the easement runs straight through the only spot it could go.
Where Experience Matters: Due Diligence Before You Build
Due diligence is where a granny flat plan succeeds or fails, and it happens long before you sign a building contract. This is the part most buyers never see.
We assess granny flat potential the same way we assess any value driver:
Does the block genuinely support a second dwelling?
What do comparable sales in the area say about the added value?
Will the build cost be recovered at resale?
Does the rental return justify the outlay?
This is where experience matters. We have spent 30+ years assessing, negotiating and securing Melbourne property, and we know how to separate a genuine value-add from an expensive lesson. Our property due diligence service is built to catch exactly this kind of problem before it costs you.
Granny flats can be one of the smartest moves a Melbourne buyer makes, but only when the planning, the permits and the site all line up. Get one of those wrong and the dream becomes a costly rebuild. If you want an independent eye on a property’s granny flat potential before you commit, Your Australian Property Buyers Agents can help. We bring 30+ years of property experience, confidential sales data and access to off-market opportunities, all working exclusively for you as the buyer. Book a free strategy call and let us check the numbers before you buy.
Frequently Asked Questions
Can you build a granny flat under 60 square metres without planning approval in Victoria?
In many cases, yes. A granny flat under 60 square metres that meets the requirements of Clause 54.03 of the Victorian Planning Scheme can proceed without a planning permit. However, this exemption depends on your property’s zoning, overlays, and specific site conditions. Always confirm with your local council before committing to any build.
What is the difference between planning approval and a building permit for a granny flat?
Planning approval assesses whether the use and development are appropriate for the site, covering matters like neighbourhood character, setbacks and amenity. A building permit, issued under the Building Act 1993 and Building Regulations 2018, confirms the structure meets safety, structural and energy standards. Both may be required, and one does not replace the other.
Can a granny flat be rented out separately in Victoria?
A granny flat can be rented separately provided it complies with the planning scheme, building regulations and local council requirements. If it sits on the same title as the main house, you will need to check whether a separate occupancy permit is required. Rental rules also cover minimum standards, bond lodgement and tenancy agreements under Victorian law.
Do granny flats need separate utility connections?
Not always. Many granny flats share utilities with the main dwelling, but separate metering may be required if you intend to rent the space independently. Water, electricity and gas connections must comply with relevant standards and council requirements. Confirm with your builder and service providers early, as retrofitting connections later adds cost and complexity.